
The digital infrastructure boom has brought major business opportunities for the banking sector this year. But tighter US restrictions on artificial intelligence chip exports to Southeast Asia have clouded the technology sector’s outlook, with the risks potentially spilling over to Singapore’s banks.
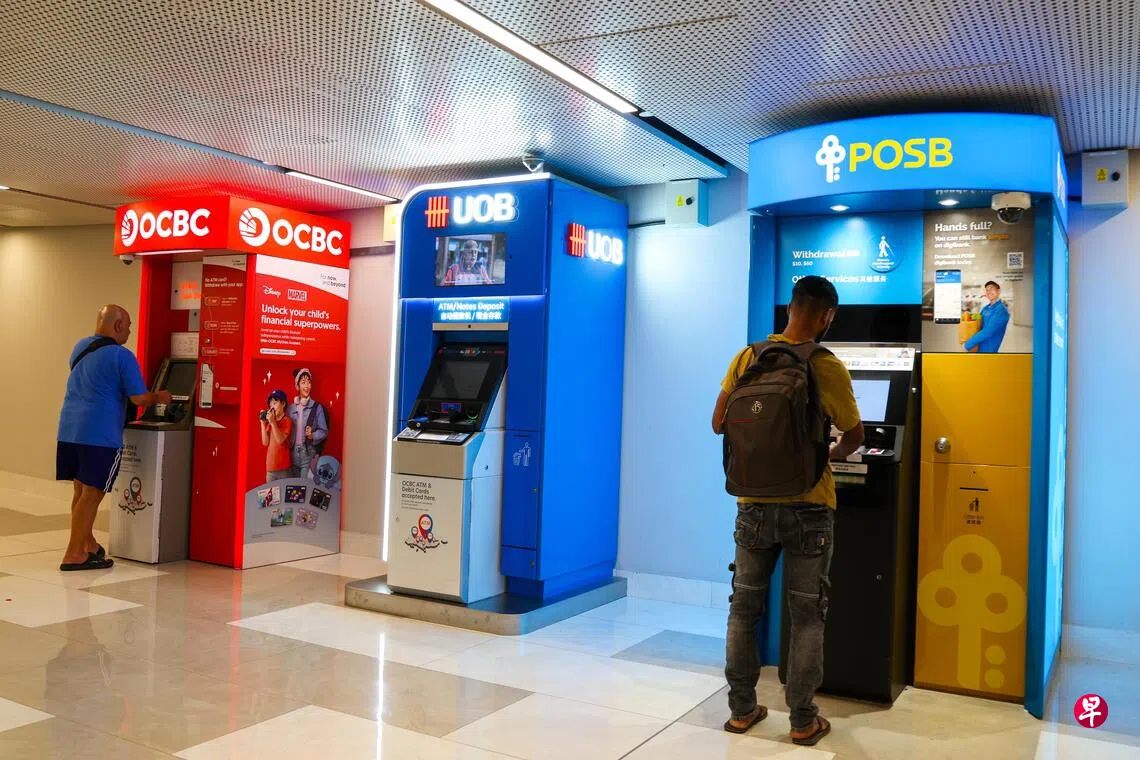
Citi Research has lowered its target prices for all three local banks. It cut its target for DBS from S$80.30 to S$78, for UOB from S$35 to S$33.90, and for OCBC from S$26 to S$25.30. However, Citi maintained its “buy” rating on DBS and “sell” ratings on UOB and OCBC.
Shares in all three banks came under pressure on Wednesday (18 November). OCBC fell as much as 2.4% to its lowest since July, UOB hit its lowest since 30 April, and DBS fell to a four-month low.
At the close, DBS was down 1.12% at S$66.94. UOB and OCBC fell 1.55% and 1.01% to S$36.13 and S$27.40 respectively.
Citi’s analysis noted that US restrictions on data centre operators in four Southeast Asian countries, including Singapore, have increased uncertainty over chip supplies. Meanwhile, forecasts for global demand for AI accelerators have been lowered. HSBC’s recent sale of a syndicated loan for a data centre project at a steep discount also points to rising credit risk in such assets. Citi has raised its forecasts for banks’ credit costs.
In recent years, the three banks have been active in data centre financing. DBS arranged more than S$20 billion in data centre financing in the Asia-Pacific region last year. All three banks also participated in a S$5 billion sustainability-linked loan for a consortium led by KKR and Singtel in September to acquire data centre operator ST Telemedia Global Data Centres (STT GDC).
The artificial intelligence boom has also driven rapid growth in global debt financing for advanced computing infrastructure, which surged to US$680 billion as of October this year — five times the total for all of 2023.
HSBC has warned that positioning in Singapore bank stocks is already crowded. About 42% of Asian equity funds are overweight Singapore, up from 20% in April 2024.
With more investment options emerging in Asian equity markets next year, HSBC advised investors to diversify their allocations and reduce concentrated holdings in popular investments such as Singapore bank stocks.
Analysts: Three banks’ exposures are well managed
Despite growing market concerns about future risks, analysts believe the risks to existing loans are limited.
CreditSights, a credit research firm owned by Fitch, estimates that data centre financing accounts for about 3% to 5% of the three banks’ total loans.
DBS has S$14.6 billion in exposure and a further S$8.98 billion in potential financing projects, together amounting to just under 5% of total loans. UOB’s short- and long-term financing exposure is below 5% of total loans. OCBC’s exposure is lower, at 3% of total loans, with other AI-related financing accounting for less than 1%.
William Tng, head of Singapore research at China Galaxy Securities, believes the three banks’ exposures are well managed.
Speaking to Lianhe Zaobao, he noted that during the oil and gas crisis in 2015, banks’ loan exposure to the sector exceeded 5% of total loans. By comparison, their exposure to commercial property loans in mainland China and Hong Kong in recent years was below 2%. He therefore believes the banking sector can weather this industry downturn relatively smoothly.
Local banks take a cautious approach to lending
A CreditSights report noted that while the three banks are optimistic about growth opportunities in data centres, they have adopted cautious and selective strategies. These include prioritising projects backed by investment-grade hyperscale data centre operators, securing long-term capacity commitments and distributing portions of loans to spread risk.
On whether these measures are sufficient to withstand potential shocks, Tng said local banks have taken the best measures currently available to them.
He noted that the three banks have maintained ample provision buffers since the pandemic, helping to cushion significant credit risks. However, a substantial rise in general provisions in future could be a warning sign of emerging risks.
Karen Wu, Director, APAC Financials, CreditSights, stressed that regulatory uncertainty stemming from the US mainly affects new lending rather than the quality of existing loans.
“Compared with some global banks, Singapore banks’ data centre business remains predominantly on their balance sheets, with capital markets business accounting for a relatively small share. Fee income growth is mainly driven by wealth management, so the impact on fees and asset quality is limited.”
She also expects the overall supply-demand imbalance in data centres to continue supporting the asset quality of existing projects.
Global banks’ financing income faces a test
CreditSights also noted that large US banks generally have limited direct credit exposure to AI and data centres, but are actively earning fees by arranging loans, underwriting bonds and providing other financing services.
As a result, if AI investment cools, multinational banks would first face slower growth in fee and lending income, rather than credit losses.
However, the firm also cautioned that AI investment has become an important driver of economic growth. A sharp slowdown in investment could increase the risk of recession, in turn weighing on banks’ loan growth and asset quality. Consumer credit would also be affected if the economic slowdown hit the jobs market.
