
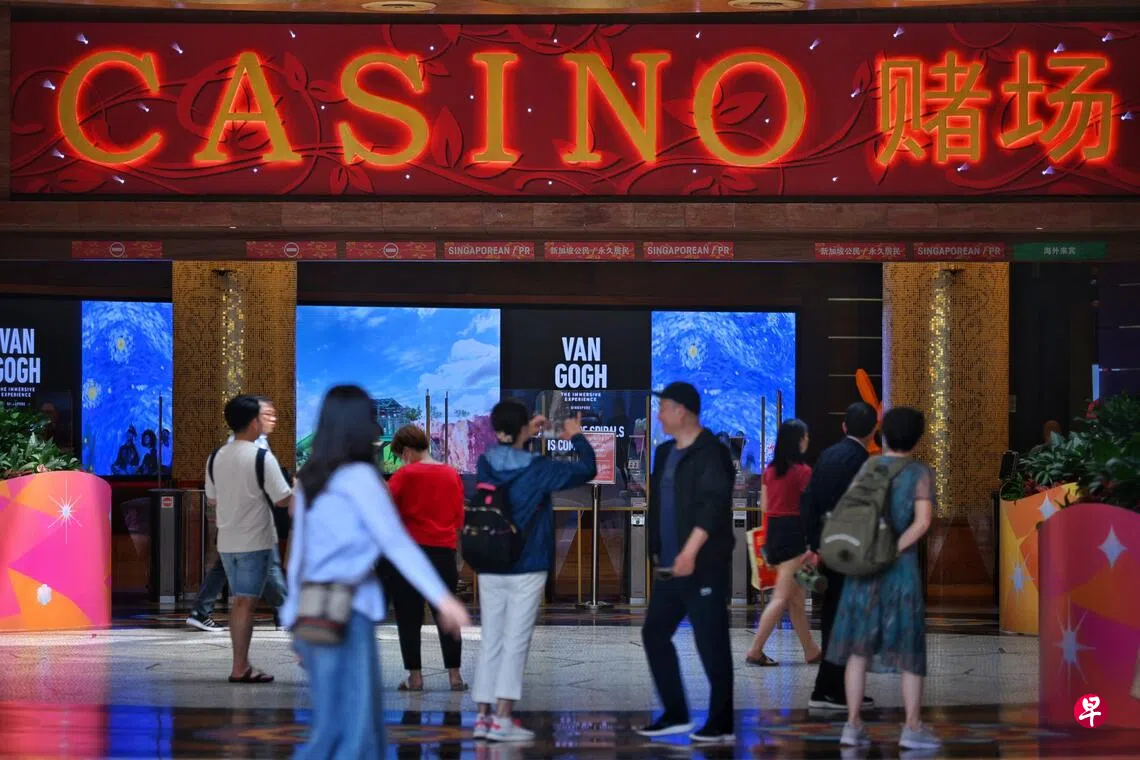
Genting Singapore shares fell for a second consecutive trading day after the company reported weaker-than-expected third-quarter results. The stock dropped more than 4% in early trading on Monday (16 November), following a roughly 6% slump last Friday (13 November), taking it close to a six-year low.
As of 11am on Monday, Genting Singapore shares were down 4.35% at S$0.55. The stock has fallen about 25% since the start of the year.
The stock previously fell to S$0.54 in October 2020.
Results released by the group after the market closed last Thursday (12 November) showed that third-quarter net profit plunged 42% year on year and revenue fell 13%, weighed down by weak casino operations. Following the results, UOB Kay Hian, Maybank and DBS all maintained their “hold” ratings, with UOB Kay Hian and Maybank lowering their target prices.
UOB Kay Hian cut its target price from S$0.70 to S$0.65 and lowered its earnings before interest, tax, depreciation and amortisation (EBITDA) forecasts for 2026 and 2027 by 7% and 10% respectively.
UOB Kay Hian analysts said in a report that weak casino operations were weighing on the company’s performance. Hotel renovations, which reduce the number of available rooms, could also affect visitor traffic at Resorts World Sentosa.
The analysts expect the ongoing renovations to reduce the number of available rooms from about 1,300 to between 950 and 1,000, potentially weighing on gaming and non-gaming revenue from the fourth quarter of this year into next year. Higher staffing, maintenance and marketing expenses will also continue to put pressure on near-term profitability.
Despite the muted earnings growth outlook, UOB Kay Hian said Genting Singapore’s dividend yield remained attractive. If the group maintains its full-year dividend of four Singapore cents per share, the yield would be about 6.6%, based on the share price used in the report.
Maybank also flagged the impact of hotel renovations on operations, cutting its target price from S$0.65 to S$0.59. Its report said the disruption was expected to last until early 2028, with reduced room availability constraining VIP and premium mass-market gaming business. It therefore lowered its earnings forecasts by 14% to 18%.
DBS maintained its target price of S$0.67, saying limited room availability would keep near-term performance subdued, with a more pronounced earnings turnaround potentially emerging only in 2028. However, its analysts also noted that the renovations would help Resorts World Sentosa narrow the gap with Marina Bay Sands in its offerings, improving its competitiveness over the medium term.
